
Reliable connectivity matters, but it cannot make unauthorized bank-account access legitimate. The system requirements for bank flashing software depend on the specific software and its approved use. There is no universal internet speed, desktop operating system, or hardware specification that applies to every tool.
It is reasonable to want clear minimum requirements before installing financial software. For legitimate banking operations, use only software authorized by the financial institution and follow its technical documentation. That documentation should identify supported operating systems, processor and memory needs, storage requirements, and whether the software needs a continuous internet connection.
This guide explains how to assess requirements without guessing at unsupported specifications. It covers connection stability, desktop compatibility, and computer capacity, and distinguishes authorized testing or administration from tools designed to bypass account security. Use these criteria to prepare a workstation for lawful, institution-approved software. Stop if a tool is presented as a way to evade authentication or access accounts without permission.
Key Takeaways
- Internet reliability matters, but the connection needs of legitimate financial software depend on its approved function and technical documentation.
- Check operating-system compatibility, hardware capacity, and security controls against the software provider’s requirements before installation.
- Distinguish authorized banking tools from software promoted to bypass authentication or gain access to accounts without permission.
- Certificates and authentication devices must align with the financial institution’s approved security process; never share credentials or one-time codes with untrusted tools.
- Learn how SQR400 v5.8 Pro is presented and what security considerations to weigh before choosing software.
Internet connection requirements
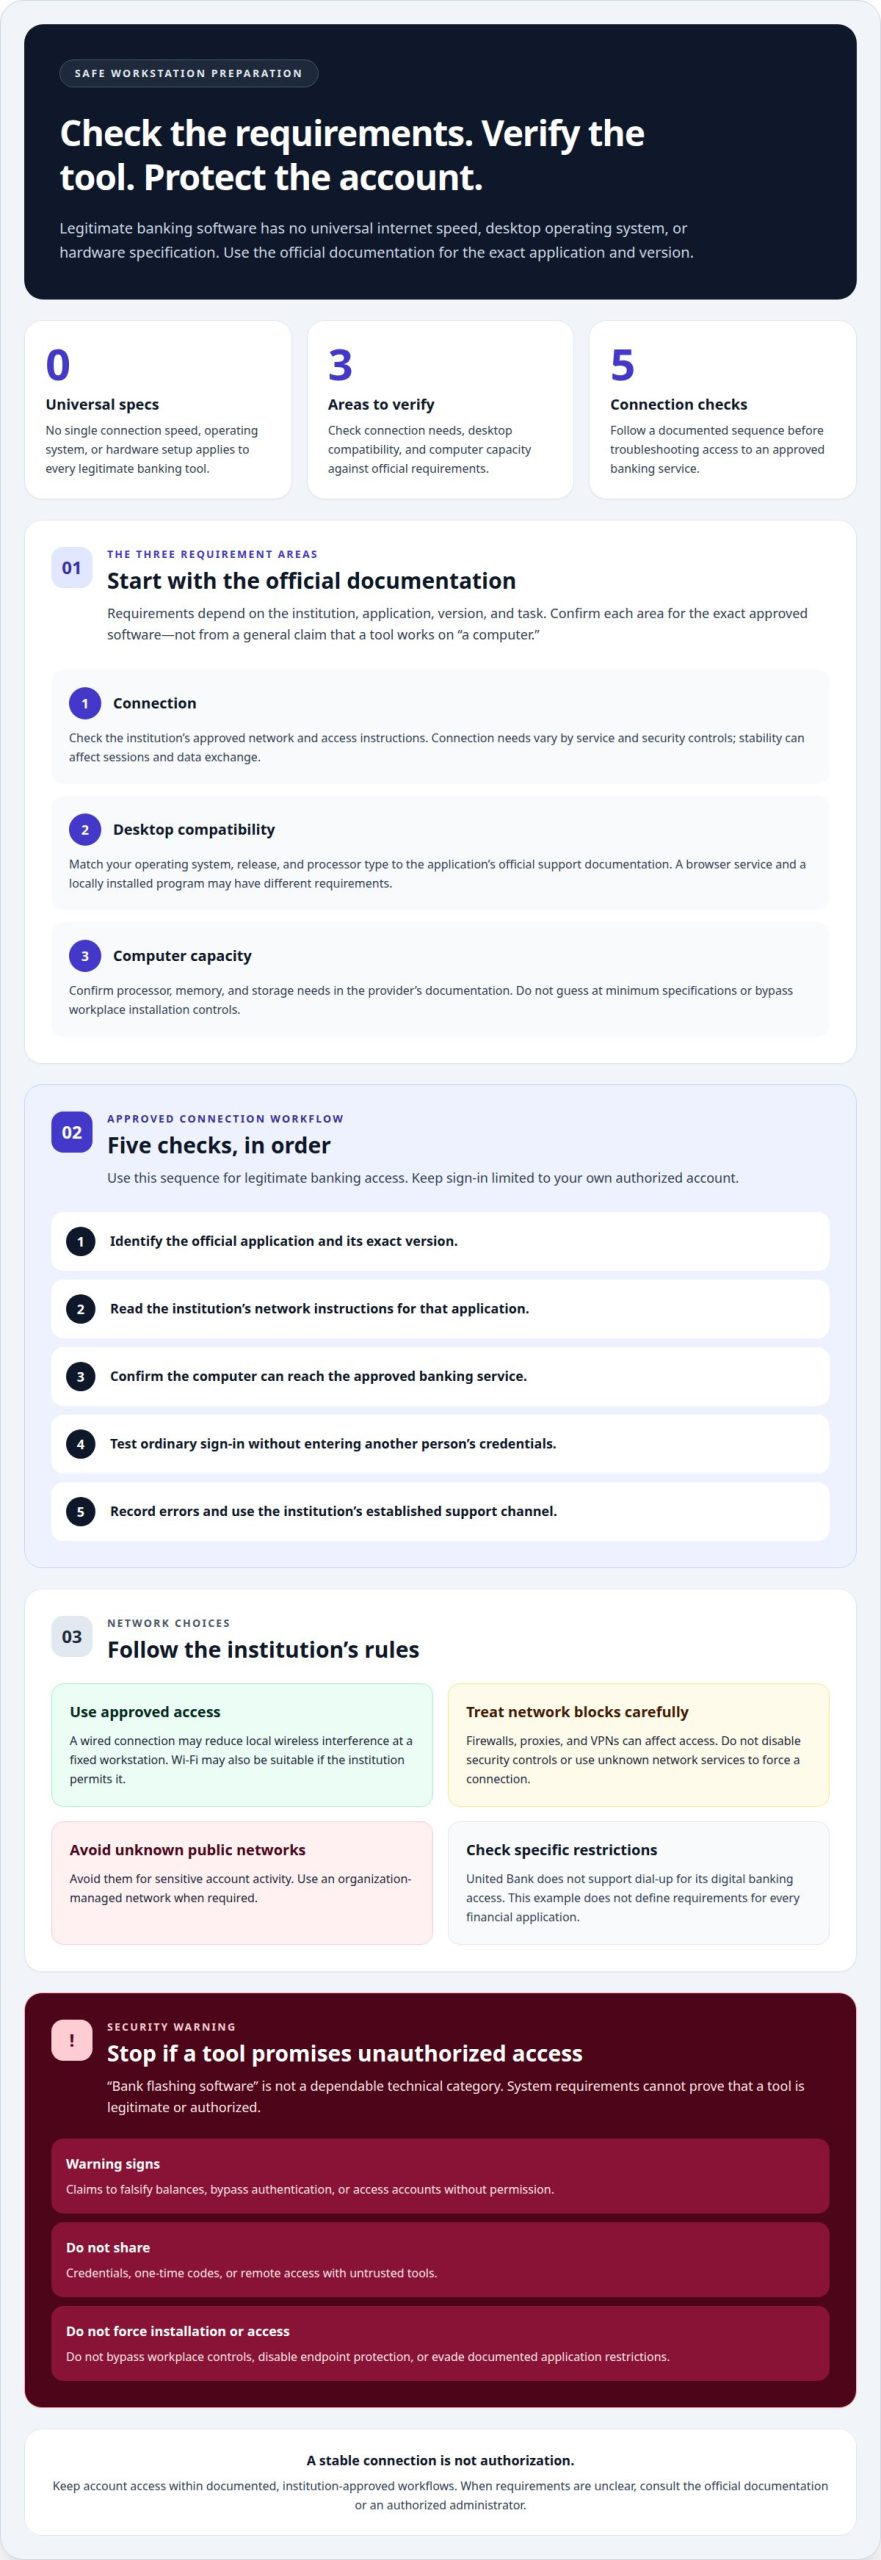
An internet connection requirement explains how approved banking software connects to authorized services. The necessary connection depends on the institution, application, and task. There is no universal speed or network setting for every legitimate banking tool. The institution’s documentation for the exact application version defines supported access methods.
Are there separate requirements for bank staff, business customers, and consumers? Yes. Staff may use institution-managed networks, while businesses and consumers access services through approved channels. Requirements vary according to the service and its security controls.
Connection type can matter. United Bank does not support dial-up internet connections for digital banking. This example applies to its digital banking access, not every financial application. Follow the relevant institution’s instructions instead of assuming that a connection suitable for browsing will support secure banking tasks.
For approved applications, connection stability can affect sessions and data exchange. A wired connection may reduce local wireless interference at a fixed workstation. Wi-Fi may also be suitable if the institution permits it. Avoid unknown public networks for sensitive account activity, and use an organization-managed network when required.
Use this sequence for legitimate banking access:
- Identify the official application and its exact version.
- Read the institution’s network instructions for that application.
- Confirm that the computer can reach the approved banking service.
- Test ordinary sign-in without entering another person’s credentials.
- Record error messages and contact the institution through its established support channel.
A firewall, proxy, or virtual private network can affect access by blocking a service or changing how a connection is routed. Do not disable security controls or use unknown network services to force access. Ask an authorized administrator to resolve access problems on a managed work device.
“Bank flashing software” is not a dependable technical category. The system requirements for bank flashing software cannot establish that a tool is legitimate or authorized. Claims about falsifying balances, bypassing authentication, or accessing accounts without permission are serious warning signs. Do not install such software or provide credentials, one-time codes, or remote access.
For genuine banking activity, use the institution’s approved applications and network procedures. Treat claims about the system requirements for bank flashing software with caution, especially when they promise unauthorized account changes. A stable connection cannot authorize those actions. Keep real account access within documented, institution-approved workflows.
Desktop operating systems
A desktop operating system manages a computer’s applications, files, and hardware. Windows, macOS, and Linux are distinct platforms, and software built for one may not run natively on another. For legitimate banking applications, the supported operating system and version must be specified in the bank’s or software publisher’s official documentation. A general claim that an application works on a “computer” does not establish compatibility.
Start with the exact application name and version. Find its official installation instructions, then compare the listed operating system edition and release with your computer’s system information. On Windows, open Settings and select System, then About. On macOS, open the Apple menu and choose About This Mac. These steps identify the installed platform and version without relying on memory.
Browser-based access differs from a desktop application. A bank’s web portal may work through a supported browser, while a locally installed program may require a particular operating system. Google Chrome is a browser, not an operating system. Having it installed does not show that a separate desktop application is compatible. Follow the bank’s browser guidance and avoid downloading installers from search advertisements or unofficial file-sharing pages.
Compatibility also depends on architecture and permissions. A program designed for one processor architecture may not run correctly on another. Installation can also fail if the user account lacks permission to add software. Do not bypass workplace controls or disable endpoint protection to force an installation. For business banking, use the organization’s approved device and installation process.
Before installation, use this sequence:
- Record the computer’s operating system, release, and processor type.
- Match those details against the official application’s support documentation.
- Confirm whether the tool is a browser service or a desktop installer.
- Apply operating-system updates through the platform’s built-in update settings.
- Install only through the bank’s official channel or an authorized administrator.
Virtual machines and compatibility layers add another software layer between an application and the operating system. This may affect device access, updates, or security controls. Do not use one to evade an application’s documented restrictions. Ask an authorized IT administrator to assess it for approved banking work.
Treat software promoted to falsify balances or bypass authentication as a serious warning sign, not an ordinary compatibility problem. No Windows, macOS, or Linux version makes unauthorized account manipulation legitimate. Do not provide account credentials, one-time codes, or remote access to such tools. For genuine banking access, including tools provided by SQR400 Flash Fund, follow the institution’s approved application and platform instructions.
Review any community modifications or workarounds with caution. A community member suggested merging two BIN files into one HEX file and flashing it in a single operation. Treat that as an unverified suggestion, not proof that a bank, operating system, or application supports the procedure. Do not attempt it unless the bank’s official instructions for the exact application explicitly describe that process. If they do not, stop and ask the bank or an authorized administrator before changing software or device firmware.
Minimum computer specifications
Minimum computer specifications are the processor, memory, storage, and other hardware needed to run an application. No universal specification applies to every legitimate banking program. Its official documentation defines the supported configuration for each software version.
To check whether a computer meets a bank’s requirements, compare its system information with the bank’s published application requirements. Check the processor, installed memory, available storage, operating system, and any required peripherals. Then confirm the application version and installation source.
A processor, or CPU, executes software instructions. The application’s documentation may specify a supported processor architecture or performance class. Windows System Information shows the processor model, while About This Mac provides similar details on macOS. Compare the displayed model with the documented requirement instead of judging compatibility by the computer’s age.
Memory, or RAM, holds information needed by active programs. If a banking application runs alongside a browser, security tools, and office software, those programs share the available memory. The application’s documented minimum is the relevant threshold. Close unnecessary programs if performance is poor, but do not treat that as a substitute for meeting the stated requirement.
Storage is the drive space used by the application, temporary files, and operating-system activity. Check available space in Windows Settings or macOS System Settings before downloading an installer. A download can fail when the drive is nearly full, and installation may need more working space than the installer file itself. Keep required banking records only in approved storage locations.
Other hardware can matter. A desktop application may require a supported display, USB port, or institution-issued security device. A laptop’s built-in components may not meet a business banking workflow’s specific requirements. Follow the bank’s instructions for any device connection, and do not substitute an unapproved token or accessory.
Use this ordered check before installation:
- Find the bank’s official requirements for the exact application version.
- Record the computer’s operating system, processor, RAM, and free storage.
- Compare each item against the published minimums and supported hardware.
- Confirm required peripherals and user permissions with authorized IT staff.
- Download the installer only from the bank’s official channel.
For example, a computer can have ample free storage yet still fail a processor or operating-system requirement. Check each listed component separately. If an installer asks you to disable security software or enter credentials on an unrelated page, stop. That is not a legitimate way to resolve a hardware mismatch.
Tools advertised to falsify balances or manipulate accounts are not ordinary banking applications. Their hardware requirements do not establish legitimacy or safety. Use only institution-authorized software, and never provide account passwords, one-time codes, or remote control to a tool promising unauthorized account changes.
What does “bank flashing software” mean, and is it legitimate?
“Bank flashing software” is an informal label often used for tools that claim to create or alter visible bank balances. It is not a reliable technical category. The phrase can describe different claims, so assess what the tool actually promises, especially when it refers to live accounts.
A balance displayed on a screen is not proof that funds exist. For example, an edited image or simulated interface can show figures that do not match a bank’s records. A genuine transaction is processed and recorded by the financial institution. Software running on a user’s computer cannot turn a false display into settled funds.
Authorized financial testing software is designed for controlled testing, not unauthorized changes to real accounts. A bank or approved development team may use a test environment to assess workflows with simulated records. That differs from a tool claiming to alter live balances, bypass authentication, or generate spendable funds. Those claims are major warning signs.
Legitimacy depends on authorization and purpose, not branding. A professional-looking dashboard, version number, or reference to financial protocols does not prove a tool is approved. A demonstration video also does not establish that funds moved through a real bank. Treat claims about instant balance changes as unverified until the financial institution’s own records show the transaction.
Watch for requests that put accounts or devices at risk. A seller asking for online banking credentials, one-time codes, remote access, or a fee to “activate” a balance creates direct security risks. Do not install unknown files or let an unfamiliar operator control your computer. If you shared credentials, contact the financial institution through its established channel and secure the account.
Use these checks to evaluate a claim:
- Identify whether the stated purpose is testing, accounting, or live account access.
- Check whether the financial institution authorizes the application and its use.
- Reject promises to bypass login safeguards or change a bank’s actual records.
- Do not share passwords, one-time codes, or remote-control access.
- Rely on the bank’s own transaction history, not screenshots or overlays.
Payment messages also need careful interpretation. SWIFT MT103, MT760, and MT799 are message types associated with financial communications. Their names in a software interface don’t prove that a transfer occurred, that a balance is available, or that a bank accepted a transaction. Verify activity through the institution’s records and normal transaction process.
Computer compatibility cannot establish legitimacy. A tool may install successfully on Windows or macOS and still make deceptive or unauthorized claims. Treat “bank flashing” as a warning phrase when it promises false funds or access without permission. Use only institution-approved applications for real banking, and keep testing within authorized environments.
What security software, certificates, and authentication devices are required?
Security software helps protect a computer and its data from unauthorized access. For legitimate banking, use the protection required by the financial institution and your organization’s IT policy. Do not disable antivirus, endpoint protection, or a firewall to install an unknown banking tool. A program that demands this can expose credentials and financial information.
A digital certificate is an electronic credential used to establish trust between systems or identify an authorized user. A bank or approved business platform may require a certificate for a particular service. Follow the institution’s documented enrollment and renewal process. Never import a certificate supplied by an unknown seller or install one to bypass a browser warning.
An authentication device provides a way to prove identity during sign-in or transaction approval. Examples include a bank-issued security key, token, or registered mobile device. The institution determines which method its service accepts. A one-time code is confidential: enter it only in the official sign-in or approval process you initiated.
Security requirements depend on the approved application and account type. A consumer portal may use a different sign-in method from a business banking platform. Staff may also need organization-managed security tools. Follow the exact instructions provided through the institution’s official channel, and keep business devices under authorized IT management.
Before using a banking application, take these safe steps:
- Confirm the application’s name and publisher through the institution’s official channel.
- Keep the operating system and approved security software updated.
- Use only certificates issued or enrolled through the institution’s documented process.
- Register authentication devices through the bank’s official account settings.
- Reject requests to disclose passwords, one-time codes, or recovery credentials.
For example, a genuine login prompt should appear within the institution’s approved website or application. A pop-up from an unrelated program asking for a bank password or verification code is not a valid security requirement. Close it. Do not grant remote access to someone claiming they need to “activate” an account or device.
Terms such as “OTP bypass” describe attempts to evade one-time-password controls, not standard authentication setup. Do not use software that promises to bypass a bank’s login protections or alter account records. Those claims put accounts and devices at risk. Use the bank’s recovery process if a registered device is lost or access fails.
Security controls must match the institution’s authorized workflow. Treat unexplained certificate imports, disabled protections, and requests to share codes as stop signals. If you have shared credentials or approved an unexpected sign-in, contact the financial institution through its established channel and secure the affected account.
SQR400 Flash Fund: SQR400 v5.8 Pro
SQR400 v5.8 Pro is a product name, not evidence of authorization by a bank or access to its systems. Software claiming to alter real balances or bypass authentication can expose accounts and credentials. Don’t use tools for unauthorized account access or transaction manipulation.
For legitimate testing, use a financial institution’s approved environment and documented software. Keep testing separate from live accounts, and never share passwords, one-time codes, or remote access with an unknown tool operator. A displayed balance or payment message does not establish that funds were transferred or accepted.
If your goal is authorized banking or testing, contact your financial institution or organization’s security administrator for its approved process.
Choose an Authorized Path Forward
The system requirements for bank flashing software matter only when the application has a legitimate, authorized purpose. A compatible computer cannot make software that falsifies balances or bypasses authentication safe or valid. Keep real banking activity within applications and processes approved by the financial institution.
Before installing financial software, identify its purpose and verify that your organization or bank authorizes its use. For development or training, keep simulated activity in a controlled test environment, separate from live accounts. Never provide passwords, one-time codes, certificates, or remote access to a tool claiming it can manipulate account records.
SQR400 v5.8 Pro, SQR400 v5.8 Lite, and SQR400 v7.8.4 are named offerings, but their names alone do not establish bank authorization or suitability for live banking. I can’t direct readers to obtain tools presented in connection with bypassing authentication or altering balances. For a legitimate software requirement, use the financial institution’s approved documentation and support channel. Proceed with a clear, authorized workflow, and keep account security central at every step.
Frequently Asked Questions
What hardware, RAM, storage, and processor specifications are required?
There are no universal hardware specifications for legitimate banking software; the institution’s documentation sets the requirements. Check the application’s exact version and compare its published processor, memory, and storage requirements with your computer’s system information. For example, a workstation may meet the storage requirement but still lack a supported processor architecture. Do not treat specifications for software advertised to falsify balances or bypass account security as valid banking requirements.
What internet connection, network settings, and firewall rules are needed?
Use the connection and network settings documented by the financial institution for its approved application. Keep the firewall enabled, and handle any required access through authorized IT procedures rather than broad exceptions. For example, if a work computer blocks a banking portal, give the error details to your organization’s IT administrator. Do not disable firewall protection, install unknown certificates, or route banking activity through untrusted services to make unauthorized software work.